By Ann Saphir
Nov 2 (Reuters) – On the eve of elections that will decide whether President Donald Trump’s Republican Party keeps control of Congress, voters’ minds are on the economy, with high and rising prices a key issue and many blaming his policies, specifically tariffs and the Iran war, for the nagging inflation.
In short, Americans are in a sour mood.
The numbers, however, tell a more complex story. On the upside, the unemployment rate remains historically low, more people than ever are employed, overall economic growth is solid and the artificial intelligence investment boom has – until recently – been driving up the stock market, padding retirement accounts for millions.
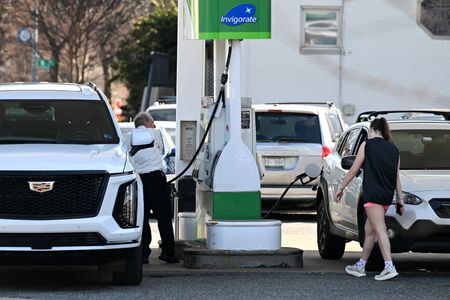
Countering that momentum, of course, is inflation. Though not nearly as high as just a few years ago, it is elevated and ever-present enough that people feel the pinch whenever they fill their gas tanks, pay a utility bill or order a meal.
Trump is not on the ballot on November 3, but voters have his economic record in mind as they head to the polls. And the vibe is skeptical, if not downright grumpy.
THE SOURPUSS ECONOMY
Consumer surveys show the mood has generally deteriorated since Trump’s second term began in January 2025, though there are nuances: One widely tracked measure of confidence published by the Conference Board perked up in October, while the University of Michigan’s consumer sentiment index registered a near-record low.
Brian Jacobsen, chief economic strategist at Annex Wealth Management, said the confidence index tracks the macroeconomy, while the sentiment index is “more personal,” asking people how they are doing financially and how affordable they find their lives to be. “Sentiment is the bigger driver of election outcomes, but confidence is the bigger driver of markets,” he said.
One argument for macroeconomic confidence derives from the labor market. Firms may not be hiring much, and new graduates are having a hard time finding jobs, but companies are not conducting mass layoffs either. Weekly unemployment insurance claims are near a 57-year low. The unemployment rate, at 4.2% in September, has measured no higher than 4.5% for five straight years – the longest stretch on record.
Households feel it. The Conference Board measures the gap between consumers who say jobs are plentiful and those who say they are hard to get, and that differential widened last month, indicating an improved outlook for jobs.
There is also the updraft from stock market gains to consider. The main US equity indexes have notched dozens of record highs this year, as Trump frequently reminds attendees at his rallies. Most Americans hold some stock, though higher-income households have disproportionately more.
Outlays by higher-income households, buoyed by the rising value of their stock holdings, have helped underpin consumer spending, which has been a strong driver of economic growth. Data last week showed the US economy grew at a 3.4% annualized pace last quarter, its strongest performance this year.
“Consumer surveys can be a little gloomy, but the consumer behavior is quite strong,” Treasury Secretary Scott Bessent told CNBC last week. “Corporate behavior is actually quite strong, and I think with tax policy, trade policy, energy policy and the regulatory policy, we’ve got a very good mix.”
AI-related demand is fueling many of the gains in the stock market and in the real economy, and business investment rose at an annualized 12.7% pace last quarter.
‘SHARP RESET’
Still, some economists warn of potential fragility – and cracks may be starting to appear.
As the midterm elections neared, a wave of corporate earnings results from the likes of Amazon.com and Intel added to growing worries about the sustainability of the AI spending boom, sending indexes such as the Nasdaq Composite sharply lower.
“A sharp reset in AI expectations could undermine corporate confidence, trigger a pullback in capex (capital expenditure) and weigh on GDP growth, just as higher oil prices, tariffs and tighter immigration restrictions push inflation higher, raising the risk of a stagflationary environment in which growth slows even as price pressures persist,” Torsten Slok, chief economist at Apollo Global Management, wrote in a mid-October note.
Putting such a dire scenario aside, any economist or Federal Reserve official will acknowledge that frustration with inflation is top of mind for many households. Although it has slowed since its 2022 peak, inflation remains well above the 2% target the central bank equates with its price-stability mandate.
For much of Trump’s second term in the White House, wages were growing faster than prices, meaning that workers could expect their paychecks to cover as much or more of the same goods and services as before.
That situation changed earlier this year after the US and Israel launched attacks on Iran in what has become an eight-month war that has lifted fuel prices globally and contributed to price acceleration more broadly. Demand for AI is also adding to inflation, Fed policymakers and economists say. Wage growth is also slowing.
Consumer prices and average hourly earnings have both risen about 5.5% since January 2025, data from the US Bureau of Labor Statistics shows. The upshot: from a purchasing-power perspective, workers are no worse off, but also no better off, than when Trump came into office in January 2025.
The US central bank raised its policy rate in September and is expected to increase borrowing costs again in December, delivering what Fed Chairman Kevin Warsh calls “monetary medicine” to bring down inflation without, he says, the need “to throw sand in the gears of the economy and throw people out of work.”
Longer-term borrowing costs have also risen, adding to the affordability woes that voters have cited as weighing on them.
The combination of 30-year mortgage rates that have topped 7% and a shortage of housing supply that has driven up home prices has conspired to put home purchases out of reach for many people.
(Reporting by Ann Saphir; Editing by Paul Simao)
Brought to you by www.srnnews.com